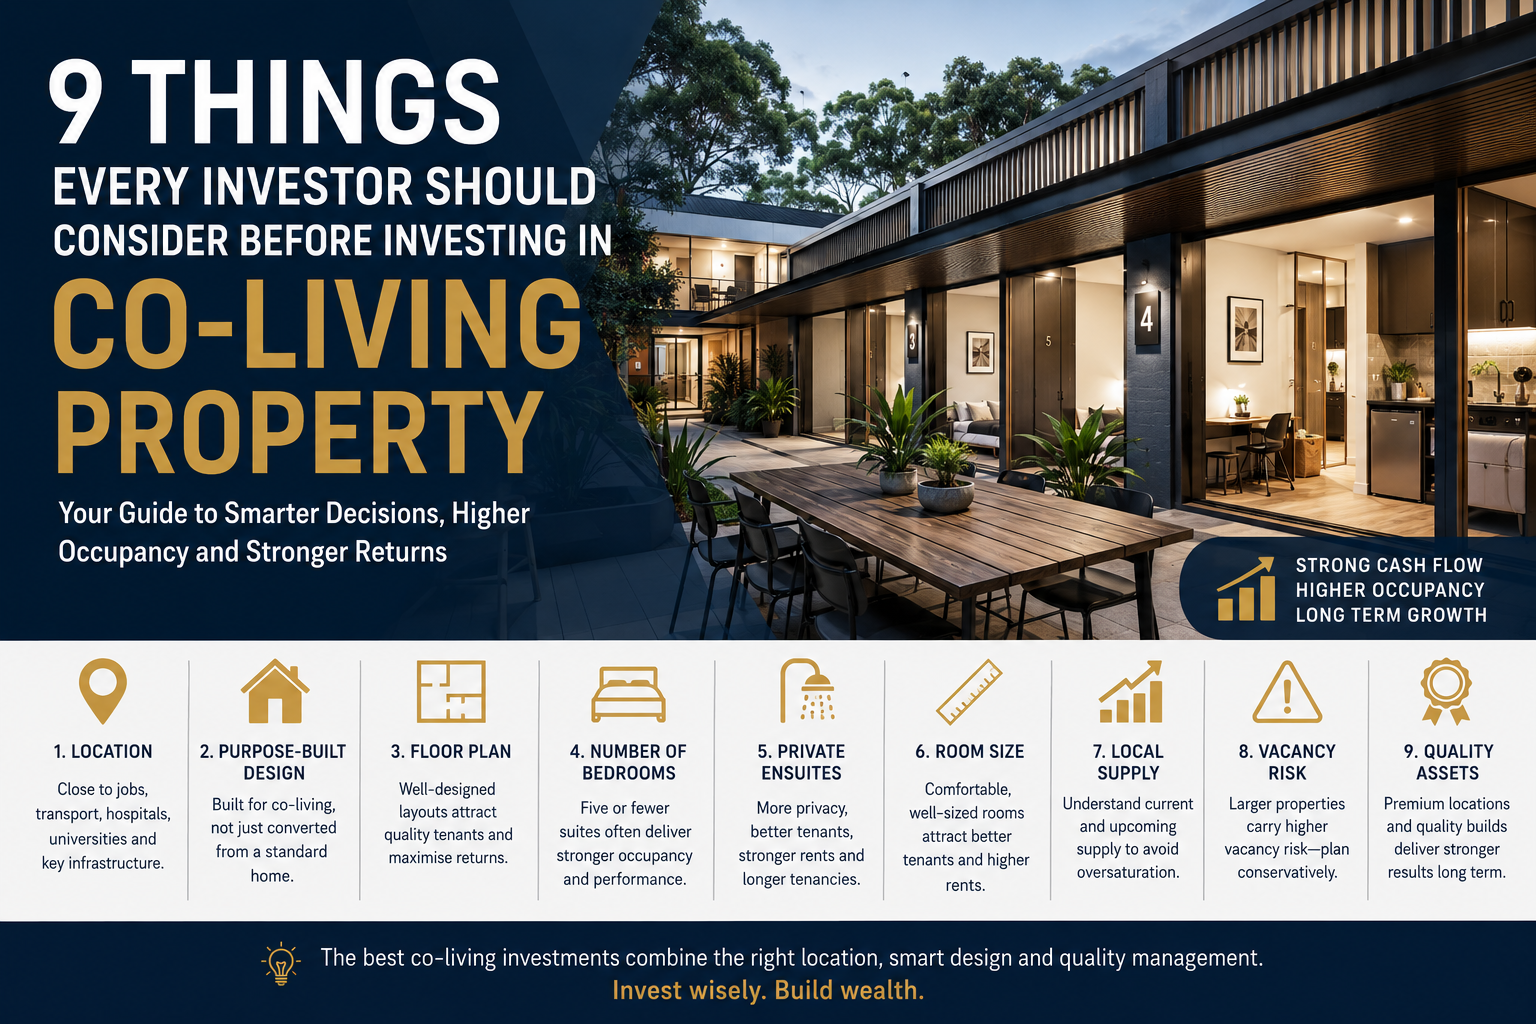
Melbourne has more renters, more students and more single-person households than almost anywhere in Australia, and the cost of renting a whole home keeps pushing people toward private rooms and suites. That makes it a natural market for co-living. It is also a market where location and compliance decide everything: Victoria has the country’s strictest rooming house rules, and Melbourne’s vacancy rate is looser than other capitals. Selectivity matters.
Why Co-Living Works in Melbourne
- Single-person households. About a quarter of Australian households are people living alone, and that share is forecast to keep rising. Many cannot afford a whole apartment.
- Students and health workers. Large university campuses and hospital precincts create steady demand for private rooms close to work and study.
- Growth corridors with new jobs. Melbourne’s west and north are adding residents faster than almost anywhere in Australia, with new hospitals, stations and employment precincts.
- Rent pressure. Melbourne’s median rent has kept climbing, which pushes more renters toward private suites as a middle ground between a share house and an apartment.
The Numbers at a Glance
| Indicator | Figure |
|---|---|
| Melbourne rental vacancy rate (SQM Research, Aug 2026) | 1.8% |
| National rental vacancy rate (Aug 2026) | 1.3% |
| Melbourne median weekly rent (DFFH, Sept qtr 2025) | $580 |
| Advertised co-living rent per suite (rental managers, 2026) | $350 to $370 per week |
| Typical co-living gross yields (properT network research) | 6% to 12%, depending on location, design and management |
Melbourne’s vacancy is higher than Brisbane, Adelaide and Perth, so poorly located or oversupplied co-living will struggle. The opportunity is in the right pockets, not the whole city.
What that rent means: rental managers are currently advertising co-living suites at around $350 to $370 per week. As an illustration only, a five-suite home at $360 per suite earns about $1,800 a week, or roughly $93,600 a year at full occupancy. At a more realistic 85% occupancy that is about $79,600 a year, before management, utilities, insurance, compliance and other outgoings. Rents vary by location, suite size and inclusions, so check current rents for the specific property.
Where We Look in Melbourne
- The west: Sunshine and its $4bn+ Superhub, Melton with a new hospital due in 2029, and Wyndham & Werribee, home to nearly 350,000 people.
- The north: Hume City and Whittlesea, with large job economies and fast-growing populations.
- The south-east: City of Casey, Victoria’s most populous council, and Cardinia Shire.
- Near hospitals and universities: health and education precincts where nurses, doctors, researchers and students need somewhere close to live.
- See every location we research on our Melbourne & Victorian locations map.
Rules You Need to Know
In Victoria, a property where rooms are available to four or more people for rent is a rooming house. The operator needs a licence, the premises must be registered with council, and the Rooming House Standards apply, including 7.5 m² minimum rooms, lockable doors and heating. Read our full guide: Co-Living & Rooming House Rules by State.
What Makes a Co-Living Property Worth Buying Here
- Location first. Walking distance or a short trip to jobs, hospitals, universities and transport. Co-living tenants rarely want to drive.
- Purpose-built design. Private suites with ensuites, good sound insulation and enough shared space. Converted older houses rarely compete.
- Not too many suites. In our experience, five or fewer suites tend to hold occupancy better than larger configurations.
- Compliance from day one. Registration, fire safety and minimum standards built in, not retrofitted.
- Realistic numbers. Model income at around 75% to 85% occupancy, not 100%, and include management, utilities and compliance costs.
- An exit. Know who will buy it from you. A property that also works as a family home or dual-income home has a wider resale market.
Read more: Co-Living Investment Guide: 9 factors to consider · Why I wouldn’t invest in a co-living property · Co-Living FAQs
Related Reading Across the properT network
- Why Australia’s shared living boom is just getting started
- Melbourne’s rental market at breaking point
- Melbourne apartment market warning
- Existing Homes vs New Builds
- Free guide: The New Property Premium
Other Co-Living Locations
Co-living in Geelong · Co-living in Ballarat & Bendigo · Co-living in Brisbane & SEQ
Frequently Asked Questions
Is co-living a good investment in Melbourne?
It can be, in the right location with the right design. Melbourne has strong demand from students, health workers and single-person households, but its vacancy rate is looser than other capitals, so location, design and compliance matter more than ever.
Is a co-living property in Melbourne a rooming house?
If rooms are available to four or more people for rent, it is generally a rooming house under Victorian law. That brings operator licensing, council registration and minimum standards.
What yield can a Melbourne co-living property achieve?
Gross yields for co-living typically range from about 6% to 12%, depending on location, configuration and management. Model your cash flow at realistic occupancy and include management, utilities and compliance costs.
Which parts of Melbourne suit co-living best?
Areas close to jobs, hospitals, universities and train lines, with limited competing supply. We research the west, north and south-east growth corridors and established employment hubs.
Talk to Us Before You Buy
Co-living can deliver strong income, but only when the location, the design, the compliance and the numbers all stack up. Book a complimentary strategy session with Stephen Lazar at properT network and we will tell you honestly whether co-living suits your goals.
Or call 0413 108 125.
Free download: The Co-Living Investor Checklist
36 checks to make before you buy a co-living or rooming house property: strategy, finance, location, state rules, management and exit. A free 9-page PDF from Stephen Lazar.
General information only. properT network does not provide personal financial, legal, tax or lending advice. Rules, rents and yields change and vary by property. Seek independent professional advice before making any decision.
